Team One Accounting on How to Save More in 2019
Patty Hansen
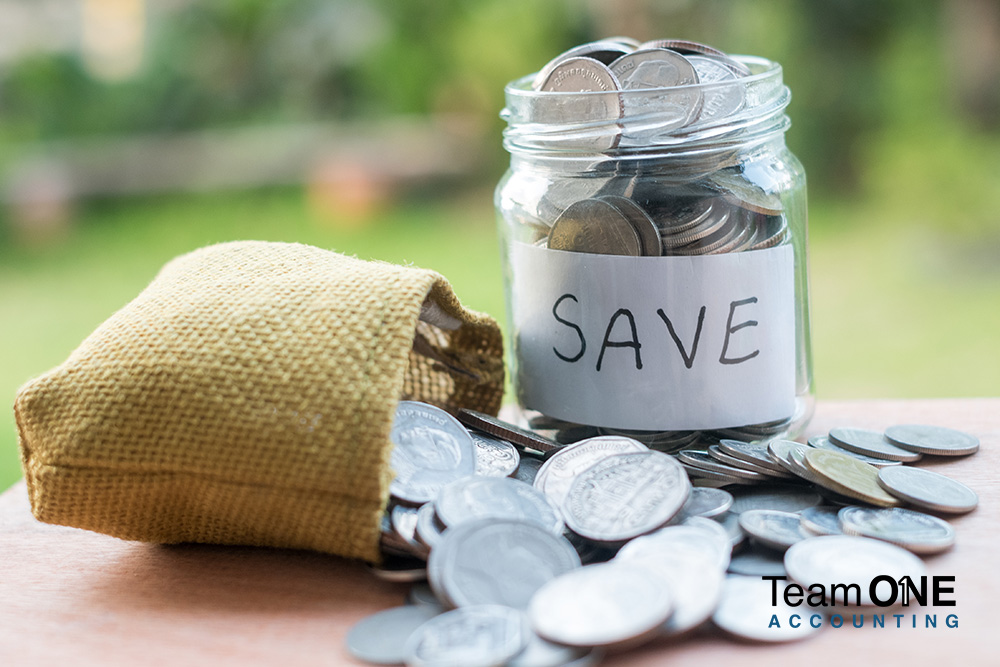
Many people in their retirement years have regrets about not saving more during their earning years, but you do not have to be one of them. All you need to do is be realistic and proactive about saving. It’s all about paying your future self.
Circumstances can arise that erode savings you hoped would be there for retirement. Some of those events include not being able to work due to poor health, a dull job market, unanticipated hospital bills, a divorce, overestimating Social Security benefits, bad investments, procrastination, or simply not realizing how much money you need to live on.
The good news is you can prevent future regrets by making a strong savings plan now. As a small business owner, you may not have a retirement plan, so it is essential that you create one for yourself. You earn an income today, put some of that income toward paying your future self, and pay that “bill” first every month or each paycheck.
Below are steps to help you be proactive and build as much savings as possible:
- Increase your financial skills by learning how to fund your retirement, including all that traveling you would like to do.
- Take care to manage your investment risk and be realistic about investment returns. In good markets, purchase rather than rent or lease so you are building an asset.
- Put as much aside as you can, and try living just below your means.
- If you do have periods where you are out of work, try living frugally until your income is back to normal.
- Optimize your business profits and apply some of them to your savings plan.
- Minimize taxes where possible so you can keep more of what you make.
- Make
everything work twice as hard for you:
- Get credit cards with loyalty programs.
- Sign up for frequent customer programs to earn points.
- Make sure your bank is giving you the best deal on interest.
- Sell unused belongings and put the money in savings.
- Cancel used subscriptions and memberships for both your personal and business needs and move the retained money to savings.
- Periodically reach out to vendors to get a better deal on the expenses you incur, like phone plans, utilities, and any other routine expense. Put the difference earned in savings.
- Select cars and trucks with good gas mileage and a high resale value.
There are hundreds of more ways to save, but these will get you started in the right direction for 2019.
Related Posts
Monsters Under the Balance Sheet: Why This Often-Ignored Report Deserves Your Attention
When business owners review their financial reports, the Profit & Loss Statement usually gets most of the attention. It makes sense. You want to know how much revenue came in, what you spent, and whether the business made a profit. But lurking just beneath the surface is another report that tells an equally important story:…
Is Your Profit Disappearing? Finding the Financial “Vampires” Draining Your Business
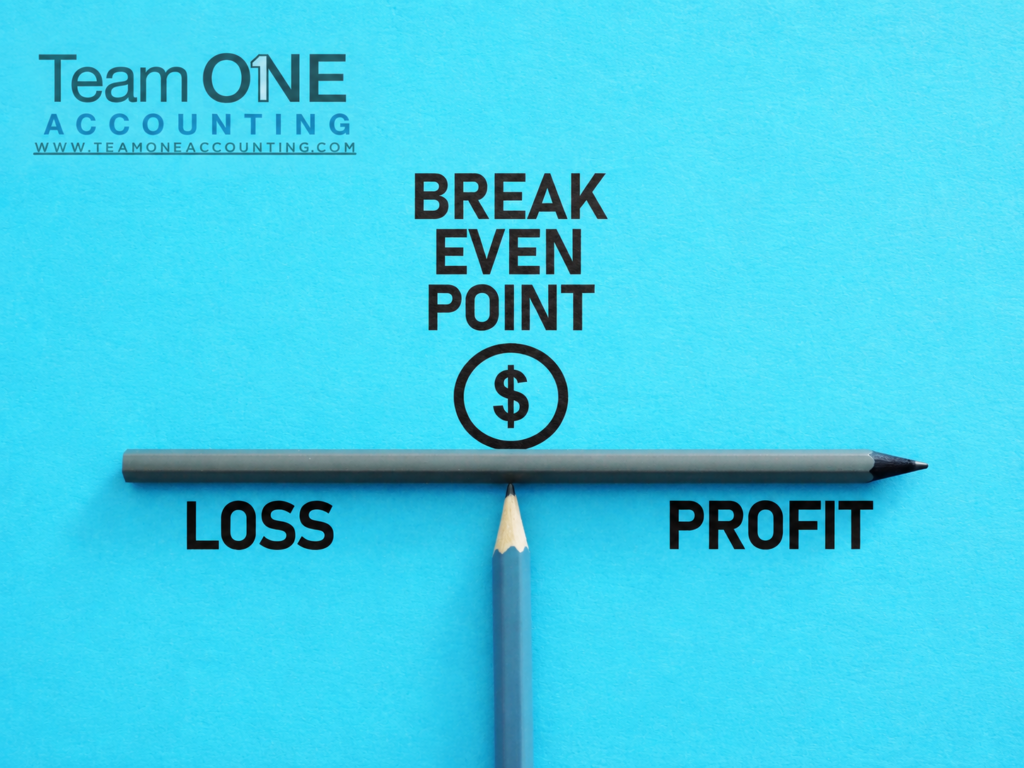
Your sales are strong. Your team is busy. Revenue looks healthy. So why does it feel like there should be more money left over? Sometimes the biggest threats to profitability aren’t dramatic expenses that immediately get your attention. They’re the smaller costs and inefficiencies quietly lurking in the background, taking a little bite out of…
Small Financial Habits That Make a Big Difference by Year-End
With fall approaching, now is a good time to make sure your books are on the right track for next year’s tax filing. When January arrives, many business owners suddenly find themselves scrambling to get their finances in order. Receipts need to be tracked down, accounts need to be reconciled, outstanding invoices need attention, and…